Oct
Opening a letter from the Internal Revenue Service that says your return has been selected for examination is unsettling, especially when you’re already juggling payroll, customers, and cash flow. Take a breath. An audit is a review, not an accusation, and most audits come down to one question: can you support what you reported?
This guide covers small business IRS audits from start to finish: what triggers them, how the process works, which records to gather, what your rights are, and when it makes sense to bring in a tax professional. Whether you run an LLC, an S corporation, or work as a sole proprietor, you’ll leave knowing your next step.
In This Guide
- What a Small Business IRS Audit Really Is
- Common IRS Audit Triggers for Small Businesses
- Correspondence, Office, and Field Audits
- The Small Business IRS Audit Process, Step by Step
- Preparing for an IRS Audit: Records to Gather
- Audit Mistakes to Avoid and Rights You Have
- After the Audit: Outcomes, Appeals, and Balances Due
- When to Get Small Business IRS Audit Help
- Small Business IRS Audit FAQs
What a Small Business IRS Audit Really Is
An IRS audit (the IRS calls it an “examination”) is a review of your tax return and records to confirm that your income, deductions, and credits were reported correctly. For a business, that can mean a Schedule C on your Form 1040, a Form 1120 or 1120-S for a corporation, a Form 1065 for a partnership, or employment tax returns like Form 941.
Returns get selected in a few main ways:
- Computer scoring: The IRS compares returns against statistical norms for similar businesses. Returns that stand out score higher.
- Information mismatches: What you reported doesn’t match the Forms 1099-K, 1099-NEC, or W-2 the IRS received from third parties.
- Related examinations: A business partner, investor, or company you work with is audited, and your return is connected to theirs.
The IRS generally has three years from the filing date to audit a return. That window can stretch to six years if income was understated by more than 25%, and there’s no time limit for unfiled returns or fraud.
Takeaway: Being selected does not mean the IRS believes you did something wrong. It means you need to be ready to back up your numbers.
Common IRS Audit Triggers for Small Businesses
No one outside the IRS knows the exact selection formula. But tax professionals see the same red flags again and again in small business tax audits. Here are the most common, and what helps reduce the risk.
| Red Flag | Why the IRS Notices | What Helps |
|---|---|---|
| Gross receipts lower than 1099-K or 1099-NEC totals | Automated matching flags the gap | Reconcile 1099s to your books and explain refunds, fees, or sales tax |
| Losses year after year | May look like a hobby rather than a business | Keep a business plan and records showing a profit motive |
| Expenses high for your industry | Meals, travel, and vehicle costs outside the norm stand out | Save receipts plus the business purpose of each expense |
| 100% business use of a vehicle | Rarely realistic for owners | Keep a written mileage log |
| Cash-heavy operations | Cash income is easier to underreport | Deposit cash regularly and keep POS reports |
| Workers paid as contractors, not employees | Possible worker misclassification | Document why workers qualify as independent contractors |
| S corporation owner paid little or no salary | Can look like avoiding payroll taxes | Pay yourself a reasonable wage through payroll |
| Mixing personal and business accounts | Makes income and deductions hard to verify | Use separate business bank and credit card accounts |
Takeaway: Most red flags aren’t proof of a problem. They’re gaps between what the IRS sees and what your return shows. Clean, reconciled books close those gaps.
Correspondence, Office, and Field Audits
Not every audit involves an IRS agent at your door. The type of audit tells you a lot about its scope.
| Audit Type | Where It Happens | What It Usually Covers |
|---|---|---|
| Correspondence audit | By mail | One or two specific items, such as a deduction or a 1099 mismatch |
| Office audit | At a local IRS office | Several items reviewed by a tax examiner, often with an interview |
| Field audit | At your business, home, or your representative’s office | A broad review by a revenue agent, often covering books, payroll, and multiple years |
One important safety note: the IRS starts an audit by mail. It does not open an examination with a surprise phone call, text, or email. If someone contacts you that way demanding payment, it’s likely a scam.
Takeaway: Read your audit notice closely. It tells you the audit type, the tax years involved, and the items under review, which shapes how you respond.
The Small Business IRS Audit Process, Step by Step
Every case is different, but most audits follow the same general path.
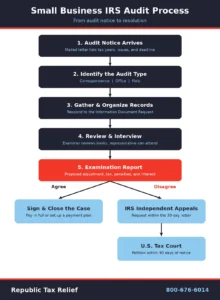
- Audit notice arrives. The letter lists the tax years, the issues, and a response deadline.
- Information request. The IRS sends an Information Document Request (Form 4564) listing the records it wants to see.
- Review and interview. The examiner reviews your records and may interview you or your representative about your business operations.
- Findings. You receive an examination report (often Form 4549) showing any proposed adjustment, extra tax, penalties, and interest.
- Agree or disagree. If you agree, you sign and the case closes. If you don’t, you can request an appeal.
Takeaway: Deadlines drive this entire process. Missing one can limit your options, so put every date on your calendar the day the letter arrives.
Preparing for an IRS Audit: Records to Gather
Good preparation is the single biggest factor you control. Start with the items listed in the IRS request, then organize the supporting documents behind each one.
Core Financial Records
- General ledger, profit and loss statement, and balance sheet
- Business bank statements, credit card statements, and canceled checks
- Invoices, receipts, and sales records that support gross receipts
Supporting Documents
- Payroll records, Forms W-2, and Forms 1099 issued and received
- Mileage logs and travel records
- Contracts, loan agreements, depreciation schedules, and inventory records
How Long to Keep Records
| Situation | Keep Records For |
|---|---|
| Most income tax records | 3 years from filing |
| Employment tax records | At least 4 years |
| Income understated by more than 25% | 6 years |
| Bad debt or worthless securities deduction | 7 years |
| Return not filed or fraudulent return | Indefinitely |
Practical Preparation Tips
- Send copies, never originals.
- Provide only what’s requested, organized and labeled by item.
- Ask for more time in writing if you need it. Examiners often grant reasonable extensions.
- Keep a log of every call, letter, and document you send.
Takeaway: Missing records don’t automatically mean you lose. They mean you need a clear plan to reconstruct what happened, and that’s where experienced help pays off.
Audit Mistakes to Avoid and Rights You Have
Mistakes That Make an Audit Harder
- Ignoring the letter. The IRS can close the audit and assess tax based only on what it has.
- Volunteering extra information. Answering beyond the question can widen the audit to new issues or years.
- Guessing during an interview. “I’ll need to check and get back to you” is a perfectly good answer.
- Changing or backdating records. Never do this. It can turn a civil audit into something far more serious.
- Missing appeal deadlines. Once a window closes, your options shrink.
Your Rights as a Taxpayer
Under the Taxpayer Bill of Rights, you have the right to be informed, to challenge the IRS’s position, to appeal in an independent forum, to finality, and to retain an authorized representative. In most cases, you can also pause an interview to consult with your representative, and your representative can attend in your place.
Takeaway: You don’t have to face the examiner alone or answer on the spot. Using your rights is not a sign of guilt; it’s how the system is designed to work.
After the Audit: Outcomes, Appeals, and Balances Due
An audit ends in one of three ways:
- No change: The IRS accepts your return as filed.
- Agreed: You accept the proposed changes and the tax deficiency.
- Disagreed: You challenge the findings.
If you disagree, you’ll usually receive a “30-day letter” explaining how to request a review by the IRS Independent Office of Appeals, which is separate from the examination team. If the dispute isn’t resolved, the IRS issues a notice of deficiency (the “90-day letter”), and you generally have 90 days to petition the U.S. Tax Court. The IRS audit overview explains these appeal rights in more detail.
If you end up owing, you still have choices. Depending on your finances, these may include an installment agreement, penalty relief for accuracy-related penalties, an Offer in Compromise, or Currently Not Collectible status if paying would cause hardship.
Takeaway: An examination report is a proposal, not a final bill. Review it carefully before you sign anything.
When to Get Small Business IRS Audit Help
Some correspondence audits are simple to answer. Others carry real financial risk. Consider professional representation if:
- You’ve received a field audit or office audit notice
- The audit covers multiple years or payroll taxes
- Your records are incomplete or need to be reconstructed
- The proposed adjustment is large or you disagree with the findings
- You also have unfiled returns or existing tax debt
A qualified representative, such as an enrolled agent, CPA, or tax attorney, can file a power of attorney (Form 2848), handle communication with the revenue agent, keep the audit focused on the issues listed, prepare your documentation, and take the case to Appeals if needed. Learn more about our business IRS audit services and business tax resolution services. We also work with industries that face unique scrutiny, including construction, medical practices, real estate, and e-commerce.
★★★★★ Google Review
“Nebulla was super helpful with getting things rolling.”
— Joseph Janner
Key Takeaways
- Small business IRS audits usually focus on whether you can support your income and deductions.
- Common triggers include 1099 mismatches, repeated losses, high expenses, and mixed accounts.
- Correspondence audits are narrow; field audits are broad and deserve professional attention.
- Respond on time, send copies, and answer only what’s asked.
- You have the right to representation and to appeal findings you disagree with.
- If the audit leaves a balance, payment plans and other relief options may be available.
Small Business IRS Audit FAQs
What triggers an IRS audit for a small business?
Common triggers include income that doesn’t match Forms 1099-K or 1099-NEC, repeated business losses, expenses that are high for your industry, cash-heavy operations, worker misclassification, and S corporation owners who take little or no salary.
How far back can the IRS audit my business?
Generally three years from the date you filed. The IRS can go back six years if income was understated by more than 25%, and there is no time limit for unfiled or fraudulent returns.
Does an audit mean I did something wrong?
No. Many returns are selected by computer scoring or because a related party was audited. An audit is a request to verify what you reported.
Can someone represent me during an IRS audit?
Yes. An enrolled agent, CPA, or tax attorney can represent you with a signed Form 2848. In most cases, your representative can communicate with the IRS and attend meetings in your place.
What happens if I disagree with the audit results?
You can request a review by the IRS Independent Office of Appeals, usually within 30 days of the examination letter. If the issue isn’t resolved, you can generally petition the U.S. Tax Court within 90 days of receiving a notice of deficiency.
What if I can’t pay the tax after an audit?
You may qualify for an installment agreement, penalty relief, an Offer in Compromise, or Currently Not Collectible status, depending on your income, expenses, and assets.
Speak With a Tax Relief Professional
Received an audit notice? Don’t wait for the deadline to get closer. Our team will review your letter, explain where you stand, and walk you through your options in a free, confidential consultation.
Request Your Free Consultation Call 800-676-6014
Your information is protected by strict client confidentiality standards and bank-grade 256-bit encryption, so you can share tax returns and bank statements with complete peace of mind.
About Republic Tax Relief
Since 2005, Republic Tax Relief has helped individuals and business owners resolve IRS and state tax problems, with more than 18,000 cases resolved. Our in-house team of enrolled agents, tax attorneys, and CPAs handles audit representation, back taxes, payroll tax issues, liens, levies, and wage garnishments. See our awards and recognition, or call 800-676-6014 to speak with our team today.