Finding out the IRS has filed a tax lien against you can make your stomach drop. A lien gives the government a claim on your home, your car, your business assets, and even property you buy later. It can stall a home sale, block a refinance, and make lenders and vendors nervous.
Here is the good news: a tax lien is not the end of the road. The IRS has clear rules for releasing, withdrawing, discharging, and subordinating liens, and most taxpayers have more options than they realize. This guide explains how a federal tax lien works, how it differs from state and property tax liens, and how an experienced professional can help you clear it.
What Is a Tax Lien and When Does a Tax Lien Arise?
A tax lien is a legal claim a tax authority places on your property when you fail to pay a tax debt. It does not seize anything. Instead, the lien secures the government’s interest so it gets paid before most other creditors if your property is sold or refinanced.
For federal taxes, the rules come from Internal Revenue Code Section 6321. It says that when a person “liable to pay any tax neglects or refuses to pay the same after demand,” the amount owed becomes a lien in favor of the United States (26 U.S.C. § 6321).
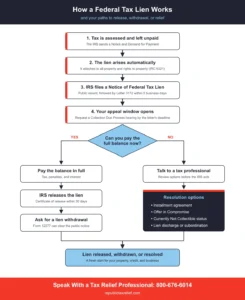
The three events that create a federal tax lien
- Assessment: The IRS records your tax liability, usually after you file a tax return or after an audit.
- Notice and demand: The IRS mails a bill asking you to pay the tax.
- Nonpayment: You neglect or refuse to pay in full by the deadline.
Once those three things happen, the lien arises automatically. The lien imposed by Section 6321 attaches to all “property and rights to property,” which includes real property, personal property, bank accounts, and business assets. It also reaches property acquired after the lien becomes effective.
The lien secures the full balance, not just the original tax. Penalties, interest, and any addition to tax are all included. The federal tax lien arising from one debt also stays in place for every tax year listed on the notice.
What is a silent lien?
Before the IRS files public notice, the federal tax lien exists quietly in the background. People often call this a silent lien. It is fully valid against you, but other creditors and buyers may not know about it yet.
Estate tax and gift tax liens work in a similar way. Under Section 6324, a special lien arises automatically at the time of death or gift, without any assessment or public filing. It generally lasts 10 years.
Tax lien vs. tax levy
People often mix up liens and levies. The difference matters because they call for different responses.
| Tax Lien | Tax Levy | |
|---|---|---|
| What it does | Places a legal claim on your property to secure the debt | Actually takes property, such as wages or bank funds |
| When it happens | Automatically after assessment, demand, and nonpayment | After a Final Notice of Intent to Levy and a 30-day window |
| Main impact | Hurts your ability to sell, borrow, or refinance | Directly removes money or assets |
| Public record | Yes, once the IRS files a notice of lien | No public filing |
How the IRS Files a Federal Tax Lien for Unpaid Federal Taxes
A silent lien becomes public when the IRS decides to file a Notice of Federal Tax Lien (Form 668(Y)(c)). The IRS records it with the county recorder, the secretary of state, or another office set by state law. Many states follow the Uniform Federal Tax Lien Registration Act, which tells the IRS where to file.
The filing tells creditors, lenders, and buyers that the existence of the federal tax lien gives the government a claim on your property. According to the IRS, the notice establishes the government’s priority against certain other creditors. The IRS often files when you owe more than $10,000, although it can file for less.
Your Collection Due Process rights
After the IRS decides to file a notice of federal tax lien, it must tell you in writing within five business days. This notice is usually Letter 3172. It gives you a deadline, generally 30 days after that five-day period, to request a Collection Due Process (CDP) hearing with the IRS Independent Office of Appeals using Form 12153.
At a CDP hearing, you can:
- Challenge whether the IRS followed the law and its own procedures
- Propose a payment plan or other alternative
- Ask for a lien withdrawal, discharge, or subordination
- Dispute the tax owed in limited situations
Missing this deadline does not end your options, but it does reduce your leverage. If you just received Letter 3172, this is the best time to call a professional.
What a Tax Lien Means for You as a Property Owner
A lien on the property you own does not force you out of your home. Still, it creates real problems, and they tend to grow the longer the lien remains.
- Selling or refinancing: Title companies and lenders will find the notice. Most will not close until the lien is paid, discharged, or subordinated.
- Getting new credit: Since 2018, the three major credit bureaus no longer show tax liens on consumer credit reports. However, lenders still search public records and often find them.
- Running a business: A federal lien attaches to business property, including equipment, vehicles, and accounts receivable. It can make it harder to get financing or sign leases.
- Future property: Any property subject to the lien includes assets you gain later, such as an inheritance.
- Bankruptcy limits: A federal tax lien may survive bankruptcy and stay attached to property you owned before filing. Read our overview on whether bankruptcy gets rid of tax debts before assuming it will help.
A federal tax lien generally lasts until the debt is paid or the IRS can no longer legally collect the tax. That period is usually 10 years from the date of assessment, but certain actions can pause or extend it.
How to Remove a Tax Lien: IRS Tax Lien Relief Options
“Removing” a lien can mean several different things. The right choice depends on your balance, your assets, and whether you are trying to sell, borrow, or simply clean up your record.
1. Pay the tax debt in full for a lien release
If you pay a tax debt in full, including penalties and interest, the law requires the IRS to release the lien within 30 days (26 U.S.C. § 6325). You will receive a Certificate of Release of Federal Tax Lien (Form 668(Z)). The IRS must also release the lien if it becomes legally unenforceable or if it accepts a bond.
2. Request a tax lien withdrawal
A withdrawal removes the public notice as if it had never been filed. You request it with Form 12277. The IRS may approve a withdrawal when:
- The notice was filed too early or without following IRS procedures
- You entered an installment agreement to pay the tax, and the agreement allows withdrawal
- Withdrawal will help you pay the debt faster
- The National Taxpayer Advocate agrees withdrawal is in your best interest and the government’s
Under the IRS Fresh Start rules, taxpayers who owe $25,000 or less and switch to a direct debit installment agreement may qualify after making three consecutive payments. You can also ask for a withdrawal after a lien is released if you have stayed current on filing and payments for the past three years.
3. Ask for a discharge of specific property
A discharge removes the lien from one piece of property, such as a house you are selling. The rest of your assets stay subject to the lien. The IRS usually expects the sale proceeds, or its share of the equity, to go toward your balance. See IRS Publication 783 and Form 14135.
4. Seek subordination of the federal tax lien
Subordination does not remove the lien. It lets another creditor, such as a mortgage lender, move ahead of the IRS in line. This is useful when a refinance or loan will lower your payments or help you pay the IRS. See IRS Publication 784 and Form 14134.
5. Resolve the underlying tax debt
Sometimes the best way to deal with the lien is to fix the debt behind it. Common paths include:
- Installment agreement: Monthly payments over time. The right terms can make you eligible for withdrawal.
- Offer in Compromise: Settling for less than you owe based on your ability to pay. Learn how the OIC program works and read our explainer on the Fresh Start program.
- Currently Not Collectible status: Pauses collection during hardship. The lien usually stays in place, but active collection stops.
- Penalty relief: Reducing penalties can shrink the balance the lien secures.
For a full overview, see our guide to tax debt relief options.
6. Wait out the collection statute
When the 10-year collection period ends, the lien becomes unenforceable and must be released. This is rarely a plan on its own. The IRS may pursue levies before then, and some actions can extend the clock.
Tax Lien Withdrawal vs. Release: What Is the Difference?
These terms sound alike, but they lead to very different results. A release of federal tax lien means the debt is resolved, yet the original tax lien notice still appears in public records, now marked as released. A withdrawal pulls the notice back entirely.
| Option | What it does | Debt paid? | Public record | IRS form or guide |
|---|---|---|---|---|
| Release | Ends the lien after the debt is satisfied or unenforceable | Yes, or statute expired | Notice stays, shown as released | Automatic; Pub. 1450 to request a certificate |
| Withdrawal | Removes the public notice as if never filed | Not always | Notice removed | Form 12277 |
| Discharge | Frees one specific property from the lien | No | Lien stays on other property | Form 14135, Pub. 783 |
| Subordination | Lets another creditor get priority over the federal tax lien | No | Lien stays | Form 14134, Pub. 784 |
A withdrawal is usually the best outcome for your record, while a release is the natural result of paying. Many clients seek both: first the release, then a withdrawal request so the notice no longer shows up in searches.
How to Get a Federal Tax Lien Released Faster
The IRS does not always move quickly, and mistakes happen. Here is what a skilled tax professional does to speed up an IRS tax lien release and protect you along the way:
- Pulls your IRS account transcripts to confirm the true balance and every tax year involved
- Checks for errors, such as a lien filed against the wrong person, a debt already paid, or an expired collection period
- Chooses the strongest path, whether release, withdrawal, discharge, subordination, or a payment plan
- Prepares and files the right requests and handles all IRS contact for you
- Follows up until the certificate of release of lien is issued and recorded, then provides copies to your lender or title company
Typical timelines
| Action | General timeframe |
|---|---|
| Release after full payment | Within 30 days |
| Discharge or subordination request | Apply at least 45 days before a sale or loan closing |
| Withdrawal request | Several weeks to a few months, depending on IRS workload |
| Direct debit agreement withdrawal | After three consecutive on-time payments |
If the IRS fails to release a lien it should have, you can ask for help through Publication 1450 or the Taxpayer Advocate Service. In some cases, federal law allows taxpayers to seek damages when the IRS knowingly or negligently fails to release a lien.
What Happens When You Don’t Pay Property Taxes: Tax Lien Sales and Tax Deeds
Federal liens are not the only type of tax lien homeowners face. Counties and cities rely on property tax to fund schools, roads, and services. When a property owner falls behind, the local tax office places a property tax lien on the real estate.
Property tax liens are powerful. Under federal law, certain local property tax liens have priority over a federal tax lien, even one filed earlier. That means the county often gets paid before the IRS.
How a tax lien sale works
Many counties hold a tax lien sale to recover unpaid property taxes. At the sale, the county may sell the tax lien to an investor, who pays the overdue amount. The investor receives a tax lien certificate, and the owner must repay that amount plus interest within a redemption period.
From tax lien certificate to tax deed
If the owner does not redeem in time, the certificate holder may be able to apply for a tax deed and take ownership. Some states skip the certificate step and sell the property itself at a tax deed sale. Rules and deadlines vary widely by state and county.
Investing in tax liens vs. owing one
You may see ads about tax lien investing and the interest returns investors earn. For a homeowner, the concern is not who is buying a tax lien. The concern is losing equity or the property itself if the property tax debt goes unresolved.
If you owe both property taxes and federal taxes, the order of payment matters. A professional can help you plan so one problem does not make the other worse.
State Tax Liens and Local Tax Debt
State tax agencies can also file liens for unpaid income, sales, or payroll taxes. A state tax lien works much like a federal one, but each state follows its own tax law and deadlines.
- Some state liens last longer than federal liens and can be renewed
- State agencies may have their own release and withdrawal rules
- A state lien and a federal lien can exist on the same property at the same time
Because state and local tax rules differ so much, it helps to have one team review every lien at once. Learn more about our IRS and state tax relief services.
Why Work With a Tax Lien Release Attorney
You can contact the IRS on your own. But the lien rules are detailed, and one wrong move can cost you months or lock you into a plan that does not qualify for withdrawal. A tax lien release attorney or other licensed tax professional brings experience with the IRS process to your side.
Here is how professional help makes a difference:
- Direct IRS representation: With a signed power of attorney (Form 2848), your representative speaks to the IRS for you.
- Strategy that fits your goal: Selling a home, refinancing, and cleaning up your record each call for a different approach.
- Negotiation know-how: Structuring a payment plan the right way can open the door to lien withdrawal.
- Error spotting: Professionals catch filing mistakes and expired deadlines that taxpayers often miss.
- Less stress: You stop dreading the mailbox and get back to your life and business.
Who can represent you before the IRS
Tax attorneys, certified public accountants (CPAs), and enrolled agents (EAs) all have unlimited rights to represent taxpayers before the IRS under Treasury Circular 230. When choosing a tax lien removal lawyer or firm, look for:
- Clear credentials you can verify
- An honest review of your options before you pay
- Written fee terms
- No promises of guaranteed results or “pennies on the dollar” for everyone
The Federal Trade Commission warns consumers to be wary of companies that make big promises before reviewing their finances. A trustworthy firm tells you what is realistic.
How Republic Tax Relief Resolves IRS Tax Liens
Our team focuses on IRS and state tax resolution. We handle the paperwork, the phone calls, and the negotiations so you do not have to face the IRS alone.
- Free consultation: We listen to your situation and answer your questions with no pressure.
- Investigation: We pull your IRS transcripts, confirm every lien filing, and identify the tax years and amounts involved.
- Strategy: We recommend the best path, whether release, withdrawal, discharge, subordination, or a broader debt resolution plan.
- Negotiation: We work with the IRS and state agencies on your behalf.
- Follow-through: We track the result until the lien is released, withdrawn, or resolved, and we help you stay compliant going forward.
Want to see the bigger picture? Explore our tax resolution services guide and our page on back tax help.
Your privacy is protected at every step. We guard your tax records under strict attorney-client and tax professional confidentiality standards, secured by bank-grade 256-bit encryption.
Tax Lien FAQs
How long does a federal tax lien last?
A federal tax lien generally lasts until the debt is paid or the collection period ends, which is usually 10 years from assessment. Some actions, such as bankruptcy or an Offer in Compromise, can pause that clock.
What is the difference between a tax lien withdrawal and a release?
A release ends the lien after you pay or the debt becomes unenforceable, but the notice stays in public records marked as released. A withdrawal removes the public notice as if the IRS never filed it.
Can I sell or refinance my home with a federal tax lien?
Often, yes. You can ask the IRS for a discharge to sell the property or a subordination to refinance. These requests should be filed at least 45 days before closing.
Will a tax lien show up on my credit report?
Since 2018, the major credit bureaus no longer list tax liens on consumer credit reports. However, liens remain in public records, and lenders and title companies can still find them.
How soon does the IRS release a lien after I pay?
The IRS must release the lien within 30 days after you pay the full balance, including penalties and interest. You will receive a Certificate of Release of Federal Tax Lien.
Do property tax liens take priority over IRS liens?
In many cases, yes. Federal law gives certain local real property tax liens priority over the federal tax lien, even if the federal lien was filed first.
Can bankruptcy get rid of a tax lien?
Bankruptcy may wipe out some older tax debts, but a properly filed federal tax lien can remain attached to property you owned before filing. Speak with a tax professional before choosing this route.
Speak With a Tax Relief Professional
A tax lien can feel like a weight you carry everywhere. You do not have to carry it alone. Our team can review your situation, explain your options in plain language, and start working toward a release or withdrawal.
About Republic Tax Relief
Republic Tax Relief helps individuals and business owners resolve IRS and state tax problems, including tax liens, levies, back taxes, and unfiled returns. Our tax professionals negotiate installment agreements, Offers in Compromise, penalty relief, and lien releases so clients can move forward with confidence. Call 800-676-6014 or contact us online for a confidential consultation.
Sources
- IRS: Understanding a Federal Tax Lien
- 26 U.S.C. § 6321, § 6323, § 6324, § 6325
- IRS Publications 783, 784, and 1450; IRS Forms 12153, 12277, 14134, 14135
- Taxpayer Advocate Service
Disclaimer: This page provides general information, not legal or tax advice for your specific situation. Tax laws change, and outcomes depend on individual facts. Consult a qualified tax professional before acting.