When part of your paycheck disappears before you ever see it, everything else gets harder. Rent, groceries, gas, and car payments all get squeezed once a creditor or the IRS starts taking a cut of your paycheck. Republic Tax Relief connects you with a wage garnishment lawyer, CPA, or enrolled agent who can act fast, file for relief, and help you get your full paycheck back.
This guide walks through how a garnishment works, how much can legally be taken from your paycheck, how the IRS actually calculates that number, and why getting legal help early gives you far more options than waiting it out.
Every pay period that passes is money you don’t get back.
Talk to a wage garnishment specialist today, free and confidential.
What Is Wage Garnishment?
Garnishment is a legal process that requires your employer to withhold part of your paycheck and send it to a creditor, the IRS, or a state tax agency until a debt is paid in full. Most garnishments start after a debtor falls behind on payments and the creditor takes the matter through court proceedings. Once a judge signs off, the court issues a writ of garnishment that tells the employer exactly how much to withhold from each check, following a court order.
The IRS works differently than a private creditor. Federal law lets the IRS send a garnishment order, called a levy, without going to court first, as long as it already mailed the required notices.1 Once that order reaches your employer, the employer is required to comply. Federal law does not give an employer a choice once a valid wage garnishment order shows up.
Debts that commonly lead to this kind of withholding include:
- Unpaid federal or state taxes
- A default on federal student loans
- Child support payments and alimony
- Credit card debt sent to a collection agency
- Medical bill balances and other unsecured debts
If you default on a repayment plan for any of these, the creditor or agency may be entitled to pursue a garnishment order as its next legal step. A wage garnishment attorney near you can tell you, in a single call, which of these rules applies to your specific notice.
How Much of Your Wage Can Be Garnished?
This is one of the first questions people ask once they are facing a garnishment for the first time. The answer depends on who is collecting the debt. For most private creditors, federal law caps the amount at the lesser of two numbers: 25 percent of disposable earnings, or the amount disposable earnings go over 30 times the federal minimum wage.2 Whichever number is smaller is the maximum a creditor has a legal right to take. Disposable earnings means what is left after required deductions like taxes, not after a voluntary deduction such as a retirement contribution.
The IRS does not use that 25 percent of disposable earnings rule. Instead, it calculates a smaller exempt amount you get to keep, based on your filing status and number of dependents, using its own formula.1 Everything above that exempt amount may be withheld and sent to the IRS with each paycheck, which in practice can leave people with far less take-home pay than a private creditor could ever legally garnish wages for.
| Type of Debt | Who Sets the Limit | Typical Amount Withheld |
|---|---|---|
| Credit card or medical debt | Federal law, Title III (CCPA) | Lesser of 25% of disposable earnings or earnings above 30x federal minimum wage |
| IRS back taxes | IRS Publication 1494 | Based on filing status and dependents; often leaves less than 25% of pay |
| Defaulted federal student loans | U.S. Department of Education | Up to 15% of disposable earnings |
| Child support (current) | State law under the CCPA | Up to 50–60% of disposable earnings (more with arrears) |
| State tax debt | State garnishment laws | Varies by state |
Certain income may be exempt from garnishment altogether, including some Social Security benefits, workers compensation, and certain retirement or disability payments. A garnishment attorney or CPA can review your pay stubs and confirm whether your employer is withholding more than the law allows.
How to Calculate Your Wage Garnishment Exempt Amount
If the IRS is garnishing your wages, the single most useful number to understand is your exempt amount, the part of every paycheck the IRS is legally required to let you keep. Everything above it is sent to the IRS. Here is the plain-English version of that formula.
What each part means:
- Take-Home Pay is what’s left in your paycheck after required deductions like federal and state income tax, Social Security, and Medicare.
- Exempt Amount is the protected portion the IRS lets you keep every pay period. It’s set each year in IRS Publication 1494 and depends on three things: your filing status, how many dependents you claim, and how often you’re paid (weekly, biweekly, or monthly).1
- Amount Garnished is everything above the exempt amount. That’s what your employer sends to the IRS each pay period, and it keeps going until the debt is paid, the collection period expires, or the levy is released.
A real-world example: Maria is single, paid every two weeks, and claims one dependent. Her take-home pay is $2,000 per paycheck. Based on the 2026 Publication 1494 tables, her biweekly exempt amount is $823.08.
$2,000 (take-home pay) − $823.08 (exempt amount) = $1,176.92 garnished
That’s nearly 59% of Maria’s paycheck gone to the IRS, well above what a typical creditor could ever legally take under the 25 percent rule.
IRS Wage Garnishment vs. Creditor Garnishment
People often lump every kind of withholding together, but IRS collection and private creditor garnishment follow very different rules.
A private collector, such as a credit card company or a medical billing office, has to sue you and win a judgment before it has the right to take money from your check. That means a lawsuit, a hearing, and a judge’s signature before anything is withheld.
The IRS skips that step entirely. Because it is a federal agency, the IRS can garnish your wages through an administrative levy once it has sent a Final Notice of Intent to Levy and given you 30 days to respond.3 No judge and no courtroom are required. This is one reason dealing with garnishment from the IRS catches so many people off guard, and why acting quickly the moment a notice arrives matters. Our IRS collections defense guide walks through that full notice timeline.
Can an Employer Fire You Over a Garnishment?
This fear keeps a lot of people from getting legal help, and it should not. Federal law gives real protection here. Under federal law, an employer cannot legally fire an employee for one garnishment tied to a single debt.2
That protection has a limit. If pay is garnished for two or more separate debts, the federal protection against being let go no longer applies, although many states extend broader protection of their own. Consult a wage garnishment attorney to understand exactly what your state adds on top of the federal minimum.
Signs You Need Wage Garnishment Relief Services
Some people wait until money is already missing from a paycheck before reaching out. Getting legal help earlier almost always creates more options. Consider reaching out if:
- You received a Final Notice of Intent to Levy from the IRS
- A collection agency sent a letter threatening a lawsuit or a garnishment order
- Your account is already delinquent on state or federal taxes
- You defaulted on a federal student loan and repayment stopped
- Your wages are being garnished right now and you cannot cover basic bills
How to Stop IRS Wage Garnishment
There is no single fix that works for every taxpayer, which is exactly why professional help matters here. A wage garnishment lawyer or CPA can help by reviewing your income, your debt, and your goals, then building a case around the option that fits your situation.
Paths a tax professional may pursue on your behalf include:
- Installment agreement: a written agreement with the IRS to pay the amount owed over time, which can stop or reduce the withholding once it is approved.
- Offer in Compromise: a debt settlement plan for less than the full amount owed, open to taxpayers who qualify based on income, expenses, and assets. See how the OIC program works.
- Currently Not Collectible status: a pause on collection efforts, including garnishment, for taxpayers who cannot pay anything right now without giving up necessities.
- Collection Due Process appeal: a formal request for a hearing that can pause the levy while your case is reviewed.
- Penalty abatement: a request to reduce penalties added to the debt, which can shrink the total amount owed.
A licensed professional negotiates directly with IRS revenue officers and creditors so you do not have to keep answering collection calls yourself. They also track the paperwork deadlines that, if missed, can put you right back where you started. If any of your tax returns are missing, our unfiled tax returns guide covers the filing step almost every one of these options requires first. If your situation involves unsecured debts far beyond taxes, an attorney can also explain when talking to a bankruptcy attorney about Chapter 7 bankruptcy or Chapter 13 bankruptcy fits into a larger financial plan, though bankruptcy is a separate legal process outside standard tax resolution work and not something this guide covers step by step.
Emergency Wage Garnishment Release
When a garnishment is already taking money out of your paycheck, speed matters. An emergency release is a request, backed by financial hardship documentation, asking the IRS or a creditor to stop the withholding while a longer-term resolution gets worked out.
To request one, your representative typically needs:
- Recent pay stubs showing how much is being withheld
- A summary of monthly income and necessary expenses
- Proof the situation is causing hardship, such as an eviction notice or a utility shutoff warning
- Any prior notices sent by the IRS or the collection agency
- Approval is not automatic, and a poorly documented request can be denied. This is one of the clearest cases where hiring a professional pays for itself, because they already know what the IRS or a creditor’s legal team wants to see before they will pause collection.
Why Work With a Wage Garnishment Attorney or CPA
Trying to negotiate directly with the IRS or a creditor while worried about your next paycheck is a hard position to negotiate from. A wage garnishment attorney, CPA, or enrolled agent brings a few things you cannot easily get on your own:
- Direct experience with exactly what documentation gets a case released faster
- The ability to talk to the IRS or a collector’s attorney on your behalf, so collection calls stop coming to you
- Knowledge of your legal right to appeal, request currently not collectible status, or negotiate a debt settlement
- A realistic read on which programs you actually qualify for, instead of guessing
You should not have to stop paying your other bills and hope the problem goes away, and you also should not have to become a tax expert overnight. Getting the right legal help early is often the difference between losing a portion of your wages for months and getting back to a normal paycheck in weeks. It generally is not worth trying to settle for less on your own without knowing the garnishment laws that actually apply to your case. For a broader look at how professional representation works across every type of tax debt, see our tax resolution services guide.
You don’t have to figure this out alone.
Get a free, confidential case review from a wage garnishment specialist.
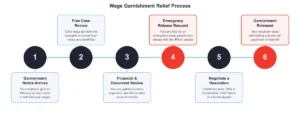
The Wage Garnishment Relief Process
Here is what working with Republic Tax Relief typically looks like from the moment a notice arrives to the day the garnishment is released.