You open your banking app, and your balance is zero. Rent, payroll, and groceries suddenly feel out of reach, and you may not even know who took the money or why.
A bank levy lets the IRS, a state tax agency, or a creditor take money directly from your bank account. A levy is rarely the end of the story, though. When people act quickly and get the right help, many are able to have their funds released, protect money the law says is exempt, and put a plan in place that stops the next levy.
This guide explains how bank levies work, your options to stop or release one, and when to bring in a professional. If you owe older balances, too, our back tax help guide covers the bigger picture.
Table of Contents
- What Is a Bank Levy and Who Can Place One?
- How the Bank Levy Process Works
- How to Stop a Bank Levy Before Money Is Taken
- How to Release a Bank Levy After Your Account Is Frozen
- Exempt Funds and the Claim of Exemption
- California Bank Levy Rules You Should Know
- Can Debt Settlement or Bankruptcy Stop a Levy?
- Why Hire a Bank Levy Attorney or Tax Relief Professional
- Mistakes That Make Collection Efforts Worse
- Bank Levy FAQs
- Speak With a Tax Relief Professional
🔒 Your privacy is protected. Every tax return, Social Security number, and bank statement you share is secured with bank-grade 256-bit encryption and handled in full compliance with federal data protection standards.
What Is a Bank Levy and Who Can Place One?
A bank levy is a legal seizure of funds in your bank account to pay a debt. Once the bank is served, it must freeze the funds up to the amount owed. After a short hold period, it sends that money to whoever issued the levy.
The rules depend on who is collecting. Tax agencies have powers that a private creditor does not.
Three Types of Bank Levies
| Who Is Collecting | Court Judgment Needed? | Legal Document Sent to Your Bank | Hold Before Funds Are Sent |
|---|---|---|---|
| IRS | No | Form 668-A, Notice of Levy | 21 days |
| California Franchise Tax Board (FTB) | No | Order to Withhold | Short; contact FTB right away |
| Private creditor (credit card, lender, medical) | Yes | Writ of execution | About 15 days to file a claim of exemption |
IRS and State Tax Levies
The IRS does not need a court order to levy your account. It must send a series of notices first, ending with a Final Notice of Intent to Levy and Notice of Your Right to a Hearing (Letter 1058 or LT11). That letter must come at least 30 days before the levy, as required by Internal Revenue Code §6330.
In California, the FTB can send an Order to Withhold to your financial institution. The Employment Development Department (EDD) can also levy for unpaid payroll taxes, which often hits business owners.
Private Creditor Levies
A private creditor has more hoops to jump through. First, the creditor must win a debt collection lawsuit and obtain a court judgment against you.
Once the creditor obtains a court judgment, it can request a writ of execution from the court. A sheriff or registered process server then delivers it to your bank, and the bank must freeze the funds in the debtor’s account.
How the Bank Levy Process Works
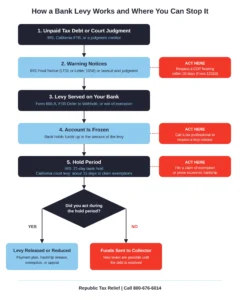
Whether it’s the IRS or a judgment creditor, the bank levy process follows a similar path:
- The debt goes unpaid. A tax bill or court judgment stays unresolved.
- Warning notices arrive. The IRS mails notices by certified mail, while a private creditor sues and wins a judgment.
- The levy is served. Once the bank is served, it must freeze your account up to the amount of the debt.
- The hold period begins. For IRS levies, the bank will hold the money for 21 days under IRC §6332(c). This window exists so you can challenge the levy or fix errors.
- Money is taken. If nothing changes, the bank sends the money to the IRS, state, or creditor.
A bank levy usually captures only the money in the account on the day it is served. Deposits made later are not covered by that levy. The IRS or creditor can place a levy again, though, and many do until the debt is resolved.
How to Stop a Bank Levy Before Money Is Taken
The best time to stop a bank levy is before your bank is ever served. Once you get a final notice, the clock is already running.
Options for IRS and State Tax Levies
These are the most common ways to stop IRS bank garnishment and state tax levies:
- Request a Collection Due Process (CDP) hearing. File IRS Form 12153 within 30 days of your final notice. In most cases, the IRS must pause levy action while your appeal is pending.
- Set up an installment agreement. Under IRC §6331(k), the IRS generally cannot levy while a payment plan request is pending or in effect.
- Request Currently Not Collectible status. If paying anything would leave you unable to cover basic living costs, the IRS may pause collection.
- Submit an Offer in Compromise. Levy action is generally suspended while the IRS reviews your offer. Learn how the OIC program works.
- Ask for penalty abatement. Removing penalties lowers the balance and may make a payment plan more affordable.
- Contact the Taxpayer Advocate Service. If a levy would cause serious financial harm, the Taxpayer Advocate Service may step in.
Options for Private Creditor Levies
With a private debt, the goal is to act before the creditor can take money. That might mean responding to the lawsuit, negotiating a payment plan, or reaching a settlement before judgment.
If you are dealing with a debt that has already gone to judgment, a professional can still negotiate. Many creditors would rather collect the money through a steady plan than chase you through the courts.
How to Release a Bank Levy After Your Account Is Frozen
If your account is frozen, stay calm but move fast. The hold period is your chance to get the money back before it’s gone.
When the IRS Must Release a Levy
Under IRC §6343, the IRS must release a levy in certain situations, including when:
- The tax debt is paid in full
- The time to collect has expired
- Releasing the levy would help you pay the debt
- You enter into an installment agreement (unless the agreement says otherwise)
- The levy creates an economic hardship, meaning you can’t pay basic living expenses
Ways a Professional Can Remove a Bank Levy
| Your Situation | Common Path to Release |
|---|---|
| You can’t pay rent, food, or utilities | Prove economic hardship with a financial statement |
| You can afford monthly payments | Negotiate an installment agreement tied to the release |
| You disagree with the IRS decision | File a Collection Appeals Program request (Form 9423) |
| The money belongs to someone else | Submit a wrongful levy claim |
| The funds are legally protected | File a claim of exemption |
For IRS bank levy help, speed matters most. A tax professional can call the IRS collection unit directly, submit your financial details, and request the release in the same conversation. In some cases, the IRS can even return money that was already taken.
Exempt Funds and the Claim of Exemption
Not every dollar in your account is fair game. Some money is exempt from levy by law, even after the bank has frozen it.
Money That May Be Protected
- Social Security benefits: When federal benefits are directly deposited, banks must protect up to two months of those deposits from private creditors under 31 CFR Part 212. The IRS follows different rules and can levy part of your benefits.
- SSI and VA benefits: These are generally protected from most creditors.
- Certain unemployment and workers’ compensation payments: These are often exempt, though protection can be harder to prove once the money is mixed with other funds.
- A minimum balance under California law: State law automatically protects a set amount in your account from court levies.
How the Claim of Exemption Works
If a private creditor levies your account, you can file a claim of exemption to protect exempt funds. In California, you generally have 15 days after the notice of levy is served to act, under Code of Civil Procedure §703.520.
Many people think they must file their exemption with the court first. In California, the claim actually goes to the levying officer, usually the sheriff. If the creditor opposes the claim, a judge then decides.
State exemption rules do not stop the IRS. Federal tax levies follow their own list of protected property in IRC §6334, so the strategy for an IRS levy is different.
California Bank Levy Rules You Should Know
A California bank levy can come from three directions: the IRS, a state agency, or a private creditor. Each one plays by slightly different rules.
- FTB Orders to Withhold: The FTB can freeze your account without going to court. It can collect state tax debt for up to 20 years in many cases.
- EDD levies: Business owners with unpaid payroll taxes may face levies on business and personal accounts.
- Court levies: A judgment creditor needs a writ of execution before it can place a levy. California law also protects a minimum balance automatically (Code of Civil Procedure §704.220).
- IRS levies: Federal rules apply, and the IRS generally has 10 years to collect under IRC §6502.
If you owe both the IRS and California, the two agencies don’t coordinate. A plan that fixes one may leave you exposed to the other, which is why a combined strategy matters. See our guide to tax relief services for IRS and state back taxes.
Can Debt Settlement or Bankruptcy Stop a Levy?
Sometimes the fastest way to end bank levies is to resolve the underlying debt. Two paths often come up.
Debt Settlement
With private creditors, debt settlement means agreeing to pay less than the full amount owed. With the IRS, the closest option is an Offer in Compromise, which is based on your ability to pay. Read more about the Offer in Compromise and Fresh Start Program.
Bankruptcy
When you file for bankruptcy, an automatic stay under 11 U.S.C. §362 halts most collection, including new levies. Chapter 7 bankruptcy may wipe out certain older income taxes that meet strict timing rules. Chapter 13 bankruptcy sets up a repayment plan instead.
Bankruptcy has serious long-term effects, and many tax debts can’t be discharged. Before you decide to file bankruptcy, it helps to compare it with IRS relief programs. Learn more in Does Bankruptcy Also Get Rid of Your Tax Debts?
Why Hire a Bank Levy Attorney or Tax Relief Professional
Some people try to handle a levy alone. The problem is that deadlines are short, the forms are technical, and one wrong statement to a collector can hurt your case.
A seasoned bank levy lawyer or tax professional knows which programs fit your situation and how to present your finances. That often means faster bank levy relief and a better long-term deal.
What a Tax Relief Professional Does for You
- Pulls your IRS account transcripts to confirm what you really owe
- Files a power of attorney (Form 2848) so the IRS contacts them, not you
- Calls the collection unit to request a levy release
- Prepares your financial statement to prove hardship or ability to pay
- Negotiates a long-term solution, so the IRS doesn’t levy again
- Keeps you informed throughout the process
Who Can Represent You Before the IRS
| Professional | IRS Representation Rights | Extra Advantage |
|---|---|---|
| Tax attorney | Unlimited | Attorney-client privilege and court representation |
| Certified Public Accountant (CPA) | Unlimited | Deep accounting and financial analysis |
| Enrolled Agent (EA) | Unlimited | IRS-licensed specialist in tax matters |
All three can represent you in IRS collection matters under Treasury Department Circular 230. Unlike general law offices that handle every kind of case, a tax resolution firm focuses on the IRS and state agencies every day.
Red Flags When Choosing Help
- Promises to settle for “pennies on the dollar” before reviewing your finances
- Large upfront fees with no clear plan
- No named attorneys, CPAs, or enrolled agents
- High-pressure sales tactics
Reliable legal representation starts with an honest review of your case. Learn more in our complete guide to tax resolution services.
Mistakes That Make Collection Efforts Worse
When you’re facing a bank levy, stress can lead to choices that backfire. Avoid these common mistakes:
- Ignoring certified mail. Missing the 30-day hearing window gives up some of your strongest rights.
- Waiting out the hold period. Once the 21 days pass, the money is usually gone.
- Moving money to hide it. This can look like avoidance and damage your chances of relief.
- Leaving past-due returns unfiled. Most IRS programs require you to be current before they will approve relief.
- Hiring help without credentials. Always confirm who will actually work on your case.
The right legal help can help you avoid these traps and protect your options.
Bank Levy FAQs
How long does a bank levy last?
An IRS bank levy usually applies only to the money in your account on the day the bank receives it. The bank holds those funds for 21 days before sending them. The IRS can issue new levies until the debt is resolved.
Can the IRS levy a joint bank account?
Yes. The IRS can levy a joint account even if only one account holder owes the tax. The other owner may be able to file a claim to recover money that belongs to them.
Can a bank levy take my Social Security benefits?
Private creditors generally cannot take up to two months of directly deposited Social Security benefits. The IRS follows different rules and can levy a portion of those benefits.
How fast can a bank levy be released?
If the IRS agrees to a release, it can sometimes happen within days. Speed depends on your situation, the documents you provide, and how quickly your representative contacts the IRS.
What is the difference between a bank levy and wage garnishment?
A bank levy takes money already in your account, usually as a one-time action. Wage garnishment takes part of each paycheck until the debt is paid or resolved.
Do I need a professional to remove a bank levy?
You are not required to hire help, but deadlines are short and the rules are complex. A tax attorney, CPA, or enrolled agent can often get faster results and a stronger long-term plan.
Will my bank warn me before a levy?
Usually not. The IRS or creditor sends notices to you, not your bank. Your bank typically learns about the levy when it is served and must freeze the funds right away.
Speak With a Bank Levy Attorney Today
A frozen account doesn’t have to turn into lost money. The sooner we review your case, the more options you have to stop the levy, release your funds, and keep it from happening again.
Speak With a Tax Relief Professional. Call 800-676-6014 or request your free consultation. Every conversation is private and confidential.
About Republic Tax Relief
Republic Tax Relief helps individuals and business owners resolve IRS and state tax debt, including bank levies, wage garnishments, liens, and unpaid back taxes. Our tax professionals negotiate directly with the IRS and state agencies to find real solutions based on each client’s finances. Call 800-676-6014 or contact us online to get started.
Disclaimer: This page provides general information and is not legal or tax advice. Tax laws change, and every situation is different. Speak with a qualified professional about your specific case.
Sources
- IRS Publication 594, The IRS Collection Process
- IRS Publication 1660, Collection Appeal Rights
- Internal Revenue Code §§6330, 6331, 6332, 6334, 6343, 6502 (via Cornell Law School’s Legal Information Institute)
- 31 CFR Part 212, Garnishment of Accounts Containing Federal Benefit Payments
- 11 U.S.C. §362, Automatic Stay
- California Code of Civil Procedure §§703.520, 704.220
- Taxpayer Advocate Service
- Treasury Department Circular 230