If you owe back taxes, you are not alone, and you are not out of options. Millions of taxpayers fall behind because of a job loss, an illness, a slow year in business, or a simple mistake that grew over time. We see it all too often, and we are not here to judge. We’ve heard it all, and we deal with it all. It’s our job, and we love fighting for our clients’ right to relief when they need it most. You work hard, and you deserve help when you need it most.
The good news is that the IRS and most state agencies offer real ways to settle a tax bill. The hard part is knowing which one fits your situation and when to pull the trigger on these programs. This guide explains your choices in plain language and shows how a qualified tax professional can get you through the process with less stress.
A word of caution before you go further: a growing number of sites and AI chatbots will hand you a generic “step-by-step” plan for resolving back taxes. The IRS does not negotiate from a script, and a plan built on general information, without your actual transcripts, income, and asset picture, is often why offers get rejected or payment plans default. Back taxes are not a do-it-yourself project once penalties, liens, or a business is involved; get someone who can pull your real numbers before you file anything.
In This Guide
- What Are Back Taxes?
- How Back Taxes Grow
- What Can Happen If You Ignore the IRS
- Which Relief Option Fits You? A Quick Self-Check
- Your Tax Debt Relief Options
- What About the IRS Fresh Start Program?
- Back Tax Help for Business Owners
- Why Work With a Tax Relief Company
- Why Not Just Use AI or Handle It Yourself?
- How the Process Works
- Real Client Feedback
- Questions People Ask About Back Taxes
- Take the Next Step
What Are Back Taxes?
Back taxes are taxes you owed in a past year and did not pay in full. They are also called past-due taxes or unpaid taxes. They can come from income taxes, self-employment taxes, or payroll taxes for a business.
Some people also have unfiled returns. That means the return was never sent in, so the IRS may have filed one for you. Sometimes the IRS lost your return, or maybe you paid someone for tax help, filed a return, and it never actually went through. When the IRS files a return for you, it rarely works in your favor, which is one reason to get help with unfiled returns early.
How Back Taxes Grow
The amount you owe does not stay the same. The IRS adds interest and penalties each month until the balance is paid. To give you real context, we have had clients owe $25,000 for a single year, and of that amount, $15,000 was just penalties and interest. That is extreme, but it is common, and it is fully legal.
- Late filing penalty: charged when a return is not filed on time.
- Late payment penalty: charged when tax is not paid by the due date.
- Interest: added daily on the unpaid balance, and it compounds.
What Can Happen If You Ignore the IRS
Letters from the IRS can feel scary, so many people stop opening them. That is understandable, but silence gives the IRS more room to act. When we bring on new clients, we ask them to send us every letter they get. We need those letters to keep our fingers on the pulse of their case. Each notice is part of the hand the IRS is playing, and the more of that hand we can see, the better chance we have of building a case that works in your favor. Notices are stressful and should not be ignored, since they warn you of what is coming, but they also give a tax professional real insight into what stage your case is at.
If a balance stays unpaid, the IRS can take steps to collect it:
- Federal tax lien: a legal claim against your property that can hurt your credit and block a sale or refinance. See our tax lien help guide.
- Bank levy: the IRS takes money straight from your bank account. See bank levy help.
- Wage garnishment: part of each paycheck is sent to the IRS before you see it. See wage garnishment relief.
- Refund offset: future refunds are applied to your old balance.
The IRS must send a Final Notice of Intent to Levy before most levies. That notice gives you 30 days to request a hearing, so do not let it sit. Source: IRS, Understanding a Levy.
State agencies work similarly, and your state comptroller or department of revenue can add penalties, freeze accounts, and place liens for unpaid state tax. State taxing authorities are often more aggressive than the IRS, since the IRS has more room to be patient and states need the cash sooner. Our IRS collections defense guide breaks down how the full collection timeline works.
Which Relief Option Fits You? A Quick Self-Check
Answer these honestly. Each “yes” points you toward a program covered below.
| Your Situation | This May Fit |
|---|---|
| I could never pay the full balance, even over time | Offer in Compromise |
| I can pay monthly, just not all at once | Installment Agreement |
| Paying anything would mean I can’t cover rent, food, or bills | Currently Not Collectible |
| My balance is mostly penalties, and I have a clean history or a real hardship reason | Penalty Abatement |
| The debt came from my spouse’s or ex-spouse’s mistake on a joint return | Innocent Spouse Relief |
| I have unfiled returns from past years | Get compliant first, before any of the above |
This self-check is a starting point, not a decision. The IRS looks at actual numbers (income, expenses, assets, equity) before approving any program, and getting the category right the first time is the difference between an approved offer and a rejected one.
Your Tax Debt Relief Options
Tax debt relief is not one program. It is a group of options, and the right one depends on how much you owe, what you earn, and what you own. Here is a quick look before we cover each one.
| Option | Best For | What It Does |
|---|---|---|
| Offer in Compromise | People who cannot pay the full amount | Settles the debt for less than you owe |
| Installment Agreement | People who can pay over time | Spreads the balance into monthly payments |
| Currently Not Collectible | People in serious financial hardship | Pauses collection while you cannot pay |
| Penalty Abatement | People with a good history or a valid reason | Removes certain penalties |
| Innocent Spouse Relief | People taxed for a spouse’s errors | Removes the tax you should not owe |
Offer in Compromise (OIC)
An offer in compromise lets you settle your tax debt for less than the full amount. The IRS looks at your income, expenses, assets, and ability to pay before it says yes. Many people are turned down because the offer was built the wrong way. Read our full breakdown of how the OIC program works.
You must be current on filing and required payments to qualify. The IRS offers a free Offer in Compromise Pre-Qualifier tool as a starting point, though it is only a rough screen, not a decision.
Installment Agreement (Payment Plan With the IRS)
A payment plan lets you pay what you owe in monthly amounts. It works well when you can afford to pay but not all at once. Interest and penalties keep building while you pay, though the penalty rate often drops once an agreement is in place.
Source: IRS, Payment Plans and Installment Agreements.
Currently Not Collectible Status
If paying would leave you unable to cover basic needs like food, rent, and utilities, the IRS may mark your account as currently not collectible. Collection stops for now, but the debt is still there, and the IRS can review your case later if your finances improve.
Penalty Abatement
Penalties can add thousands of dollars to a bill. The IRS may remove some of them if you have a clean record or a good reason for the problem, such as a serious illness or a natural disaster.
Source: IRS, Penalty Relief.
Innocent Spouse Relief
If your spouse or former spouse caused an error on a joint return, you may not have to pay the extra tax. This option depends heavily on the facts of your case, so a professional review helps.
Source: IRS, Innocent Spouse Relief.
What About the IRS Fresh Start Program?
You may have heard about the “Fresh Start” program. It was a set of IRS changes that made it easier for taxpayers to qualify for payment plans, lien relief, and settlements.
Today, “fresh start” is often used as a general phrase for these relief programs. A tax professional can tell you which ones you may actually qualify for right now, which matters more than the label.
Back Tax Help for Business Owners
Small and large businesses face added risk. Unpaid payroll taxes are treated seriously, and owners can be held personally responsible for part of the debt through the Trust Fund Recovery Penalty. This is not a corner to cut, since it can follow you personally even if the business closes.
If you own a business and owe back taxes, these steps matter:
- Act before a levy hits your business bank account.
- Keep current payroll and estimated taxes while you settle the old balance.
- Get a plan that protects cash flow so you can keep operating.
Business cases often mix federal and state debt, so one plan should cover both. See our guide to business tax debt relief for more on how we structure these cases.
Why Work With a Tax Relief Company?
You can talk to the IRS on your own. But the process is paperwork heavy, and one wrong number can lead to a denial. Professional tax relief services take the load off you and aim to get the best result the rules allow. We have been practicing this for over 20 years, and we know the agents, the forms, and the timing that actually moves a case forward.
Here is what a good team does for you:
- Reviews your full tax history and balance with the IRS and your state.
- Files a power of attorney (IRS Form 2848) so they can speak for you.
- Helps you get missing returns filed.
- Builds and submits your relief request with the right proof.
- Handles calls, letters, and deadlines so you do not have to.
Who Is Qualified to Help?
Only certain professionals can represent you before the IRS. These include attorneys, CPAs, and enrolled agents. Enrolled agents are tax experts licensed by the IRS itself, and our team includes licensed enrolled agents with decades of combined case experience.
Ask who will actually work on your case and what license they hold. You can also read the IRS guidance on choosing a tax professional.
Red Flags to Watch For
The IRS warns that some companies make promises they cannot keep. Be careful if a company:
- Guarantees it can settle your debt for pennies on the dollar.
- Charges a large fee before it looks at your records.
- Will not tell you who is doing the work.
- Pressures you to sign right away.
A trustworthy tax relief company reviews your facts first, then tells you honestly what is possible. Source: IRS, Tax Relief Company Warning.
Why Not Just Use AI or Handle It Yourself?
It is tempting to ask an AI chatbot to draft your offer or to copy a “DIY back tax” checklist you found online. The problem is that those tools do not have access to your IRS transcripts, your real income and expense numbers, or your state’s specific collection rules, so they cannot tell you what you will actually qualify for.
A generic plan built this way is one of the most common reasons an offer in compromise gets rejected or a payment plan gets set too high to keep up with. Back taxes are a negotiation with real deadlines and real consequences, not a form-filling exercise, so get your actual numbers in front of a licensed professional before you submit anything.
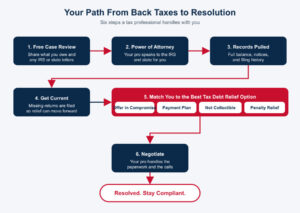
How the Process Works
Here is what most cases look like from your first call to the finish line.
Real Client Feedback
Results matter more than promises. Here is what one client shared after working with the Republic Tax Relief team.
| Client | Review |
|---|---|
| elliew | “Thank you Republic Tax! Your whole team worked hard for me and got my tax debt that had been stressing me out for years resolved. Its nice to be able to sleep great and not have to worry about the IRS taking my hard earned money. Thank you Chris for your expertise and Nebula for walking me through each step.” |
Questions People Ask About Back Taxes
Can I owe back taxes and still get help if I cannot pay?
Yes. Options like an offer in compromise and currently not collectible status exist for people who cannot afford to pay the full amount.
Will the IRS take my bank account or paycheck?
It can, but only after certain notices. Acting early may stop a bank levy or wage garnishment before it starts.
How long does the IRS have to collect?
In most cases, the IRS has 10 years from the date a tax is assessed. Some events can pause that clock, so your exact timeline should be checked by a professional.
Can the Taxpayer Advocate Service help me?
The Taxpayer Advocate Service is an independent group within the IRS. It can step in when you face hardship or when normal channels fail. It does not replace a tax professional who builds your case.
Do I have to file my missing returns first?
In most cases, yes. The IRS wants you in tax compliance before it approves a relief program. Your tax professional can guide you through this part.
Find more answers on our Back Tax Help Questions page →
Take the Next Step
Back taxes rarely fix themselves. The longer they sit, the more interest and penalties you pay, and the closer the IRS gets to a levy. A generic plan or an AI-generated checklist will not change those deadlines, but a professional who can see your actual numbers can.
You do not have to sort this out alone. Call 800-676-6014 to talk through your situation with the Republic Tax Relief team, or request your free case review below.
Speak With a Tax Relief Professional